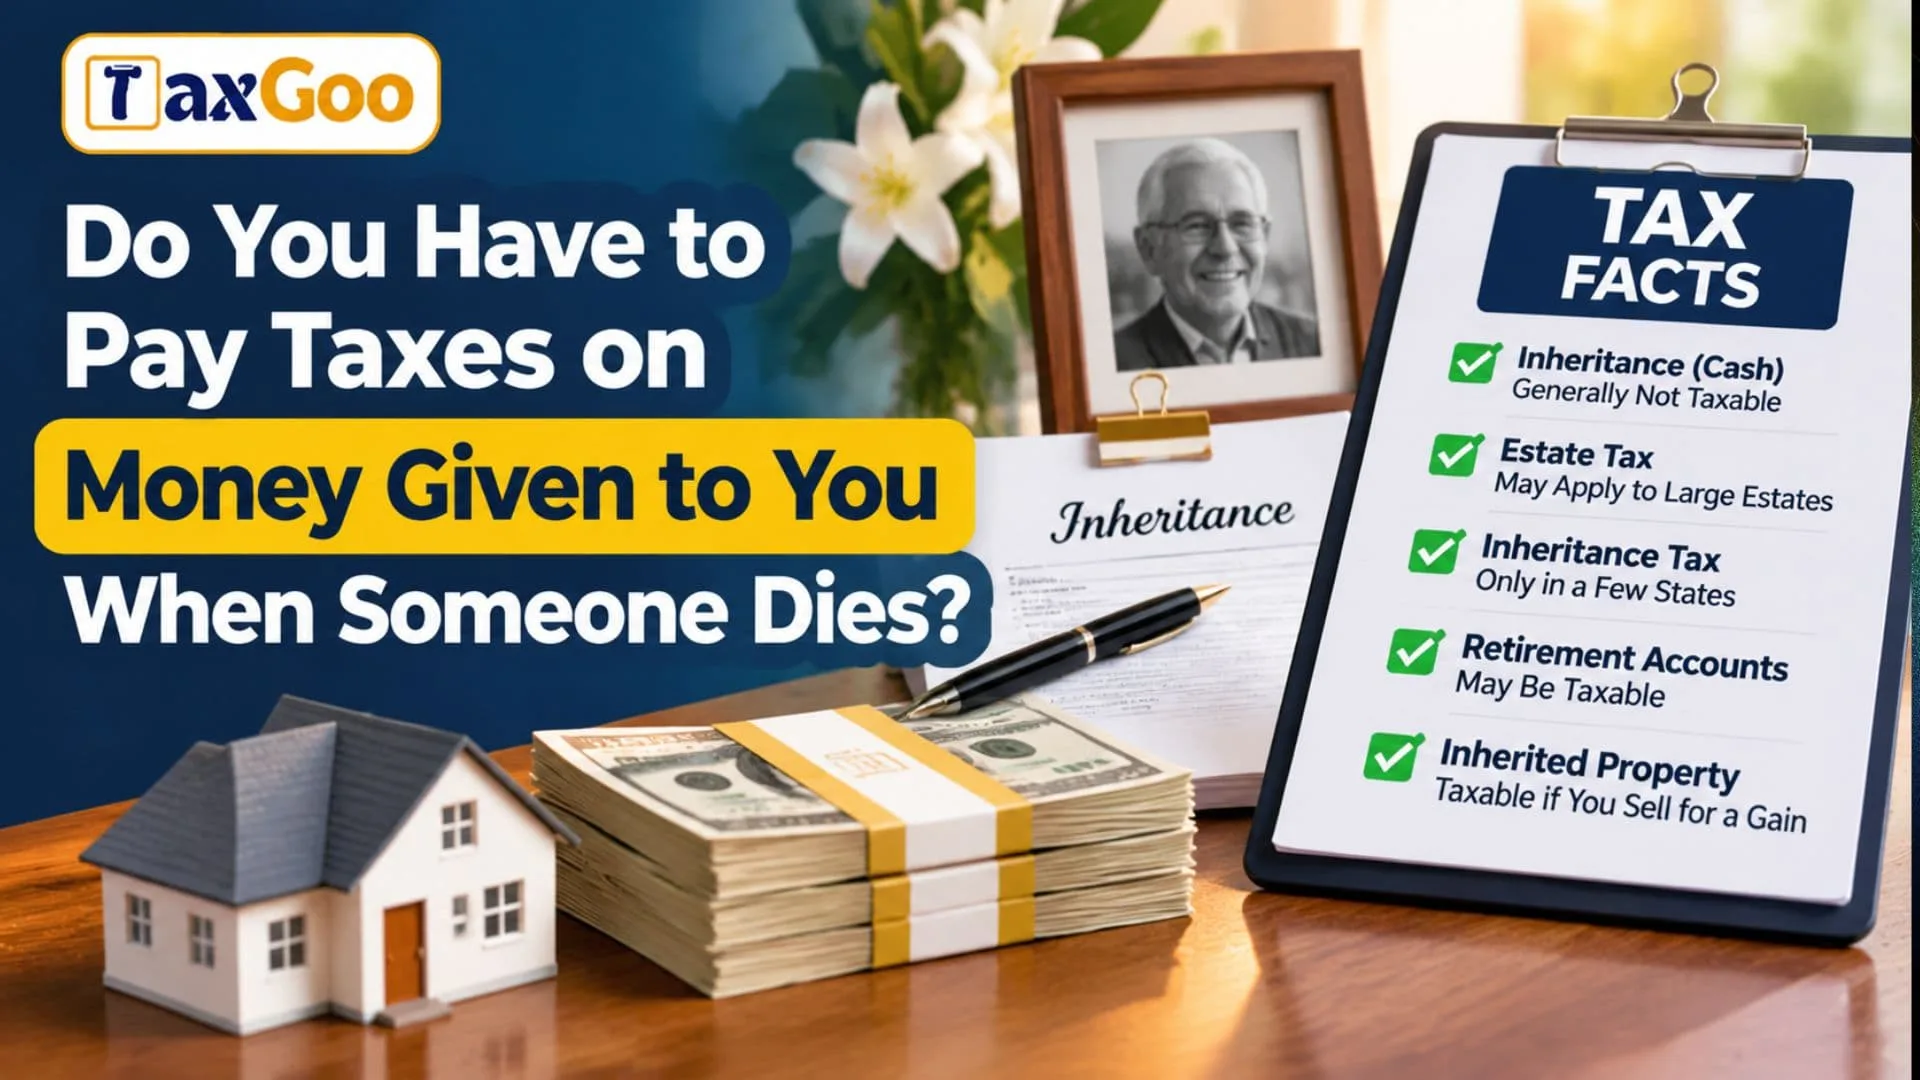
Do you have to pay taxes on money given to you when someone dies? In most cases, the answer is no. If you receive money, property, or other assets as an inheritance from a deceased family member, friend, or another individual, the IRS generally does not consider the inheritance itself taxable income. This means you usually do not have to report inherited cash as ordinary income on your federal income tax return. However, that does not mean every inheritance is completely tax-free. Depending on what you receive, where you live, and how the estate is handled, you may encounter federal estate taxes, state inheritance taxes, or income taxes on certain inherited assets. For example, receiving $50,000 in cash from a parent’s estate is generally not a taxable income event for the beneficiary. However, withdrawing money from an inherited traditional IRA, collecting interest from inherited savings, or selling inherited investments for a profit may create tax obligations. The person who passes away may also have an estate that owes taxes before assets are distributed to beneficiaries. Understanding the difference between inheritance tax, estate tax, and income tax can help you avoid unexpected bills and manage inherited money more confidently.
Is Inherited Money Considered Taxable Income?
Generally, no. The IRS excludes money and property received as gifts, bequests, and inheritances from the recipient’s gross income.
For example, imagine your uncle leaves you $30,000 in his will. You receive the money through the estate’s executor. Under general federal income tax rules, you do not owe ordinary income tax simply because you received that inheritance.
The same general treatment applies to many inherited assets, including:
- Cash and bank deposits
- Personal belongings
- Jewelry and collectibles
- Real estate
- Stocks and other investments
However, income generated by inherited property after the owner’s death may be taxable.
What Is The Difference Between Estate Tax And Inheritance Tax?
These two taxes are often confused, but they work differently.
Estate Tax: This tax applies to the deceased person’s taxable estate. It is generally paid by the estate before assets are distributed to beneficiaries.
Inheritance Tax: This tax is imposed on certain beneficiaries who receive inherited property. Whether you owe it can depend on the state, the amount inherited, and your relationship to the deceased.
For federal estate tax purposes, the 2026 basic exclusion amount is $15 million. Generally, an estate exceeding the applicable threshold may need to file an estate tax return and could owe federal estate tax.
Not every estate owes this tax, and beneficiaries do not automatically become responsible for the deceased person’s federal estate tax.
Do You Pay Taxes On Inherited Cash?
In most situations, inherited cash is not subject to federal income tax.
For example:
| Inherited Cash | Federal Income Tax On Receiving It |
|---|---|
| $5,000 | Generally $0 |
| $20,000 | Generally $0 |
| $50,000 | Generally $0 |
| $100,000 | Generally $0 |
| $250,000 | Generally $0 |
These examples assume the money is an ordinary inheritance rather than taxable income distributed through another arrangement.
State inheritance taxes may still apply, depending on the location and circumstances.
Are Inherited Retirement Accounts Taxable?
Retirement accounts are an important exception to understand.
If you inherit a traditional IRA, you may owe income tax when you withdraw taxable funds. The money generally becomes taxable when distributed to you, rather than simply when you inherit the account.
For example, suppose your father leaves you a traditional IRA worth $80,000. You generally do not owe income tax just for becoming its beneficiary. However, taxable withdrawals from that account are generally included in your income.
Inherited Roth IRAs have different rules. Qualified distributions are generally tax-free, although certain nonqualified distributions may include taxable earnings.
Beneficiaries should also understand the applicable withdrawal deadlines and distribution requirements before moving or withdrawing retirement funds.
Do You Pay Taxes On Inherited Property?
Inheriting a house, land, or other property generally does not create immediate federal income tax liability.
However, selling that property later could result in capital gains tax.
Inherited property generally receives a tax basis equal to its fair market value on the date of the owner’s death. This is commonly called a stepped-up basis.
For example, suppose your mother purchased a house for $150,000, and it was worth $350,000 when she passed away. If you inherit the property and later sell it for $360,000, your potential taxable gain may generally be based on the difference between $360,000 and $350,000, rather than the original $150,000 purchase price.
Actual calculations can depend on property improvements, valuation rules, selling costs, and other circumstances.
Which States Charge Inheritance Tax?
Federal inheritance rules are not the same as state tax rules.
As of 2026, five states impose inheritance taxes:
- Kentucky
- Maryland
- Nebraska
- New Jersey
- Pennsylvania
Each state has its own exemptions and tax rates. Some beneficiaries may receive favorable treatment based on their relationship to the deceased, while others may have to pay tax on qualifying inherited assets.
For example, Maryland generally exempts immediate family members, including spouses, children, grandchildren, parents, and siblings, from its inheritance tax. Other beneficiaries may face different rules.
If you inherit property or money from someone who lived in one of these states, check the applicable state requirements before assuming the inheritance is tax-free.
What Should You Do After Receiving An Inheritance?
Taking a few practical steps can help you avoid unnecessary tax problems.
- Keep Inheritance Documents: Save the will, estate distribution statements, and other relevant paperwork.
- Identify The Assets: Determine whether you received cash, investments, real estate, or retirement accounts.
- Check State Tax Rules: Find out whether the estate or inheritance is subject to state taxes.
- Understand Investment Income: Track interest, dividends, rental income, and other earnings generated after the inheritance.
- Review Retirement Accounts: Understand withdrawal requirements before taking distributions.
- Consult A Tax Professional: Seek professional guidance if the estate includes substantial assets or complicated tax arrangements.
Final Thoughts
So, do you have to pay taxes on money given to you when someone dies? Generally, no. Most inherited cash and property are not considered taxable income under federal law. However, estate taxes, state inheritance taxes, inherited retirement account distributions, and income generated by inherited assets can create tax responsibilities. Before spending, selling, or withdrawing inherited assets, take time to understand the rules that apply to your particular situation. A little preparation can help you protect your inheritance and avoid unnecessary tax surprises.
Frequently Asked Questions
Do I Have To Report Inherited Money To The IRS?
Generally, no. Ordinary inherited cash is not considered taxable income and usually does not need to be reported as income.
Is Money From A Deceased Parent Taxable?
Generally, no. Money inherited from a parent is usually exempt from federal income tax.
Do I Pay Taxes If Someone Leaves Me $100,000?
Generally, no federal income tax is due simply because you inherit $100,000 in cash. State inheritance tax rules may differ.
Can The IRS Take My Inheritance?
An ordinary inheritance is not automatically subject to federal income tax. However, certain unpaid tax obligations, estate liabilities, or legal claims may affect inherited assets.
Do I Pay Taxes When I Sell An Inherited House?
You may owe capital gains tax if you sell the property for more than its applicable tax basis.
Is An Inherited IRA Taxable?
Traditional inherited IRA distributions are generally taxable when withdrawn. Qualified inherited Roth IRA distributions are generally tax-free.