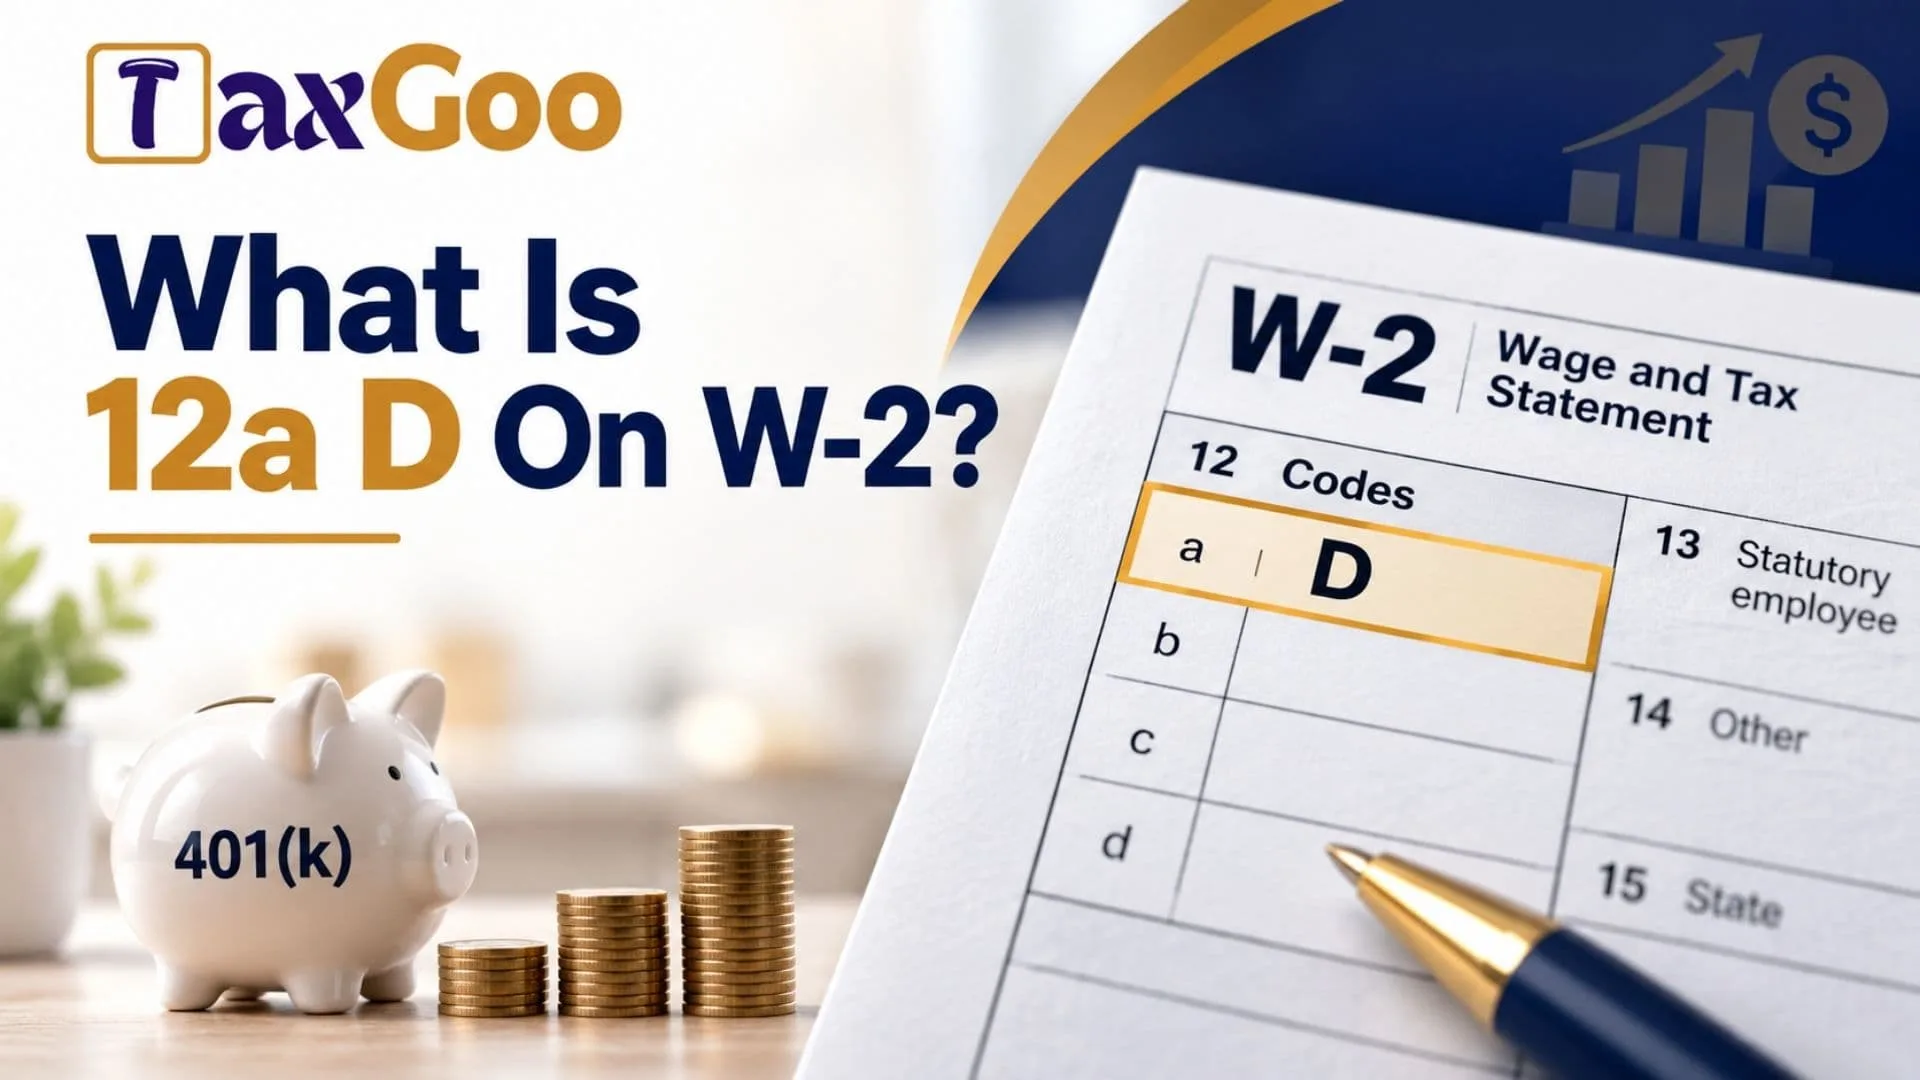
If you are asking what is 12a D on W-2, the answer is much simpler than the wording makes it seem. On Form W-2, “12a” is the first entry line inside Box 12, while Code D identifies employee elective deferrals made to a traditional 401(k) plan, including a SIMPLE 401(k) arrangement. In plain English, the amount beside D is generally money you chose to put into your 401(k) from your pay during the year. These W-2 Box 12 Code D contributions are commonly called 401(k) elective deferrals or pre-tax 401(k) contributions. They usually reduce the wages shown in Box 1 for federal income tax purposes, although they are generally still included in Social Security and Medicare wages. That is one reason Box 1 may be lower than Boxes 3 and 5. Understanding the 12a D W-2 meaning helps you review retirement contributions, spot possible payroll errors, and enter your W-2 correctly when preparing your tax return.
What Does 12a Mean on a W-2?
Box 12 can report several types of compensation, benefits, and retirement plan information. The spaces labeled 12a, 12b, 12c, and 12d are simply separate lines for those entries.
The “a” in 12a is not Code A. If your W-2 shows D 5000.00 in 12a, the 12a tells you where the entry appears, while D tells you what the amount represents. The IRS explains that Box 12 codes are not connected to whether they appear in 12a, 12b, 12c, or 12d.
What Does Code D Mean in Box 12?
Code D means elective deferrals under a Section 401(k) cash or deferred arrangement. It also covers employee deferrals under a SIMPLE 401(k).
For example, if your W-2 shows 12a D 6,500.00, that generally means $6,500 of your compensation was deferred into a qualifying 401(k) plan during the year. It does not mean you owe an extra $6,500 in tax. It is a reporting entry showing how much of your pay went into that retirement plan.
Does Box 12 Code D Reduce Taxable Income?
Traditional pre-tax 401(k) elective deferrals are generally excluded from the wages reported in Box 1. This can lower the income subject to federal income tax for that year.
However, those deferrals are generally still subject to Social Security and Medicare taxes. That is why a contribution may be excluded from Box 1 while still being included in Boxes 3 and 5.
You normally should not subtract the Code D amount again on your tax return. Your employer has generally already reflected the pre-tax treatment in Box 1, so claiming it again could incorrectly reduce taxable income.
Is Code D the Same as a Roth 401(k)?
No. Traditional 401(k) elective deferrals are generally reported with Code D, while designated Roth 401(k) contributions use Code AA.
Traditional pre-tax contributions generally reduce current federal taxable wages. Roth 401(k) contributions are made with after-tax dollars and generally do not reduce Box 1 wages. Checking the code helps you understand which type of contribution your W-2 is reporting.
Why Should You Check the Code D Amount?
You usually do not need to do anything special just because Code D appears on your W-2. Still, compare the amount with your final pay statement or retirement plan records.
This is especially useful if you worked for more than one employer and contributed to multiple 401(k) plans. Annual employee contribution limits generally apply across qualifying plans, and those limits can change from year to year.
If the number looks wrong, contact your employer or payroll department. If a correction is necessary, your employer may need to issue a corrected Form W-2.
Are Employer Matching Contributions Included in Code D?
Generally, no. Code D is used for employee elective deferrals. IRS instructions state that employer matching contributions and certain nonelective employer contributions are not reported in Box 12 as Code D.
If you contributed $5,000 and your employer added a $2,000 match, you should not automatically expect Code D to show $7,000. The Code D amount normally reflects your qualifying employee deferrals.
What About Box 13 Retirement Plan?
You may also see the “Retirement plan” checkbox marked in Box 13. That checkbox indicates retirement plan participation under applicable W-2 reporting rules.
Box 13 and Code D are related to retirement benefits, but they serve different purposes. Code D reports qualifying employee deferrals, while Box 13 identifies retirement plan participation. Box 13 can also affect certain rules for deducting traditional IRA contributions.
The Bottom Line
When you see 12a D on a W-2, focus on the D. Code D generally means employee elective deferrals to a 401(k) plan, while 12a simply tells you it is the first coded entry in Box 12.
For most employees, the tax treatment is already reflected in the wages reported on the W-2. Check the amount against your records, enter it accurately when requested by tax software, and contact payroll if something looks wrong.
Frequently Asked Questions
What Does D Mean in Box 12 of a W-2?
Code D generally reports employee elective deferrals to a 401(k) plan, including a SIMPLE 401(k).
Do I Deduct Box 12 Code D Again?
Usually, no. Traditional pre-tax Code D contributions are generally already excluded from the federal taxable wages reported in Box 1.